Last Updated: November 14, 2026
Quick Summary
To claim a tuition tax credit, enter the eligible tuition fees from your T2202 certificate on Schedule 11, which produces a non-refundable federal credit. Then complete the provincial schedule, choose whether to use, transfer or carry forward any unused amount, and check that everything flows through to your return.
- Use the eligible tuition figure printed on your T2202, not the total you paid the school.
- Enter the eligible fees on line 32300 of the federal schedule, Schedule 11.
- The federal credit is calculated by multiplying eligible fees by the lowest federal rate of 15%.
- Use the credit against your own tax first, then transfer or carry forward any remainder.
- Students who cannot use the full credit may transfer up to an annual maximum to a parent or grandparent.
Table of Contents
- What the Tuition Tax Credit Is and Who Qualifies
- Gathering Your T2202 Tuition and Enrolment Certificate
- Step-by-Step: Entering Your Tuition on Schedule 11
- Carrying Forward Unused Tuition Amounts
- Transferring Your Tuition Credit to a Parent
- Fixing Missing Slips and Claiming Prior-Year Tuition
- Filing Your Return With Lira Tax & Accounting
- Frequently Asked Questions
Every January, thousands of Canadian students open their tax package and find a slip they barely remember receiving. That slip, the T2202, is the key to the tuition tax credit, and This guide walks through how to claim the credit, step by step.
The tuition tax credit is a non-refundable credit that reduces the federal income tax a student owes.
What the Tuition Tax Credit Is and Who Qualifies
The tuition tax credit lowers the tax you owe, not your taxable income. It only works when you owe tax, which means a student with little or no income may not be able to use it right away.
To qualify, the course generally needs to be taken at a qualifying educational institution, such as a university, college, or certain other post-secondary schools (Eligible tuition fees). Canada Revenue Agency guidance on eligible tuition fees
Keep these points in mind:
- Eligible tuition fees are the costs the institution charges for courses that qualify.
- Full-time or part-time status matters, since part-time students may qualify for a smaller amount.
- Non-refundable means the credit reduces tax payable but does not create a refund on its own.
Gathering Your T2202 Tuition and Enrolment Certificate
Your school issues the T2202 (or a similar certificate) each year. It shows the eligible tuition fees you paid and the months you were enrolled. New arrivals filing their first Canadian return can see what else to gather before starting.
Before you file, gather these items:
- Your T2202 or equivalent tuition certificate for each school
- Your student number and the school's name
- Proof of fees paid, if the school asks for it later
Step-by-Step: Entering Your Tuition on Schedule 11
This is the part most filers get wrong, because the tuition amount passes through several lines before it becomes a credit. Work through it in order, whether you are using certified tax software or a paper return.
- Confirm your slip type first. A T2202 from a Canadian institution goes on the federal tuition schedule. If you studied outside Canada, you need a TL11A (university outside Canada), TL11C (commuter to a U.S. institution), or TL11D (educational institution outside Canada for a dependant), and the amounts are entered differently. Canada Revenue Agency guidance on tuition tax certificates
- Enter the eligible tuition fees on line 32300 of the federal schedule (Schedule 11). Use the figure printed on your T2202, not the total you paid the school, the slip already excludes non-eligible fees such as student activity fees, health and dental plans, and most ancillary charges.
- Enter the months of full-time and part-time enrolment in the columns provided. These months matter because they feed the part-time and full-time education amounts and because they must reconcile with the slip.
- Calculate the federal amount. Schedule 11 multiplies eligible fees by the lowest federal rate (15%) to produce the non-refundable federal tuition amount. That figure flows to line 32300 of your return as a federal non-refundable credit.
- Complete the provincial or territorial schedule. Most provinces and territories administer their own tuition credit on their own schedule . The provincial credit is calculated separately on the provincial schedule, so the same tuition can produce a different provincial credit.
- Decide what happens to the unused amount before you file. On Schedule 11 you must choose whether to use the current-year amount, carry it forward, or transfer it.
- Verify the flow-through. Check that the amount on line 32300 of your return matches the federal credit calculated on Schedule 11, and that the provincial schedule shows the corresponding provincial credit.
A worked example makes the mechanics concrete. Suppose a student paid $6,000 in eligible tuition in Ontario and has $400 of federal tax payable. The federal credit is $6,000 × 15% = $900. The student uses $400 to wipe out federal tax, transfers up to the permitted maximum to a parent, and carries the rest forward. The family should look at both the federal and provincial results before deciding how much to transfer.
Watch out: entering the total amount you paid the school instead of the eligible tuition figure on the T2202 overstates the credit.
The table below summarises the Schedule 11 steps, so you can check each line before you file.
| Step | What to do | Note |
|---|---|---|
| 1. Confirm slip type | Identify whether your T2202 or a TL11 form applies | Outside-Canada studies use TL11A, TL11C or TL11D |
| 2. Enter eligible fees | Enter the T2202 figure on line 32300 | Not the total you paid the school |
| 3. Enter enrolment months | Record full-time and part-time months | Must reconcile with the slip |
| 4. Calculate federal amount | Multiply eligible fees by 15% | Non-refundable federal credit |
| 5. Complete provincial schedule | Calculate the provincial or territorial credit separately | Can differ from the federal amount |
| 6. Choose unused-amount treatment | Use, transfer or carry forward | Decide before you file |
| 7. Verify flow-through | Check line 32300 matches Schedule 11 | Confirm the provincial credit matches too |
Carrying Forward Unused Tuition Amounts
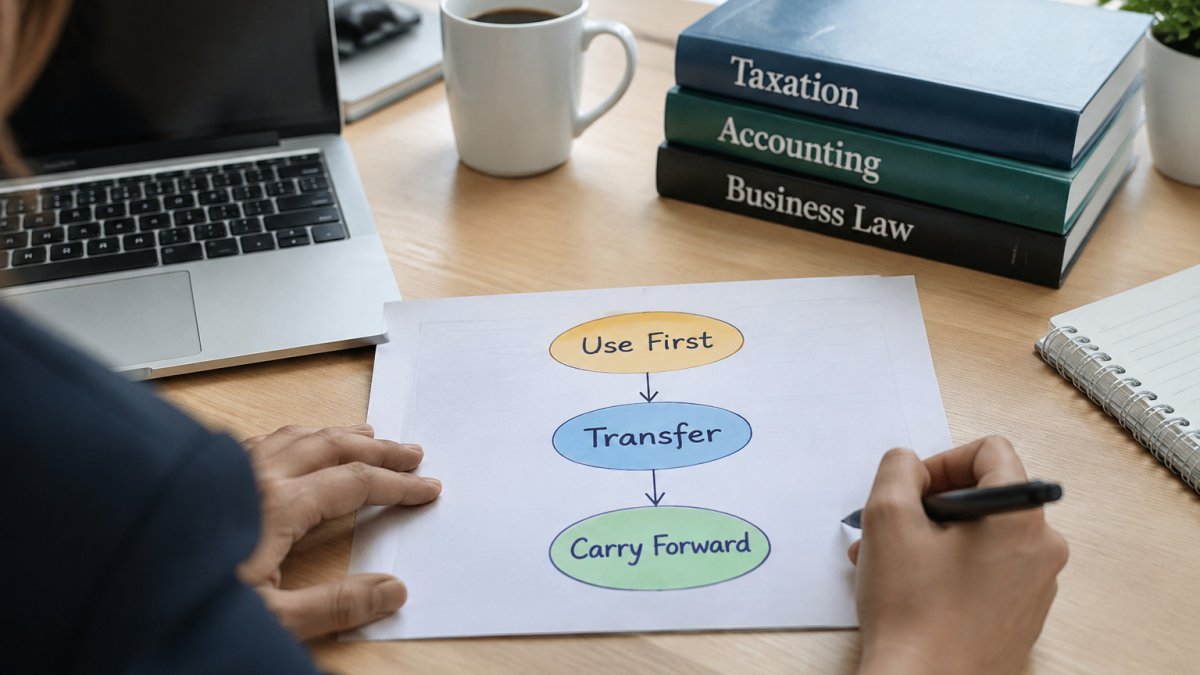
Unused tuition does not vanish, but what you can do with it depends on a short decision tree. Work through it in this order before you file.
Step 1, Use the current-year amount against your own tax first. The current-year tuition amount is generally applied against the student's own federal tax payable before any transfer or carry-forward. If the student owes no tax, the entire amount is available to transfer or carry forward.
Step 2, Decide whether to transfer or carry forward. Only the amount the student cannot use against their own tax is available. From that remainder, the student may transfer up to the annual maximum to a spouse or common-law partner, a parent or grandparent, or the spouse or common-law partner of a parent or grandparent. Whatever is not transferred is carried forward.
Step 3, Carry forward the rest. Carried-forward amounts are claimed on the relevant schedule in a future year. Keep the T2202 and a record of the carry-forward.
A decision tree in practice:
- No tax payable, no transfer wanted: carry the full unused amount forward on Schedule 11.
- No tax payable, transfer wanted: transfer up to the annual maximum to an eligible family member and carry the rest forward.
- Some tax payable: use the credit against your own tax first, then transfer the remainder up to the maximum, then carry forward whatever is left.
- Tax payable exceeds the credit: nothing to transfer or carry forward this year.
A worked example: a student in British Columbia paid $8,000 in eligible tuition and has $200 of federal tax payable. The federal credit is $8,000 × 15% = $1,200. The student uses $200 against their own tax, leaving $1,000. If the annual transfer maximum is $5,000, the student can transfer the full $1,000 to a parent and carry nothing forward, or transfer less and carry the balance forward for a future year when their income is higher. The right choice depends on the parent's marginal rate versus the student's expected future rate.
Watch out: transferring the full amount to a parent in a year the student could have used it themselves can waste the credit, because the parent may be in a lower tax bracket than the student expects to be in later. Run both scenarios before choosing.
Transferring Your Tuition Credit to a Parent
Students who cannot use the full credit may transfer up to a set amount to a parent, grandparent, or spouse. The transfer reduces the supporting person's tax, so the family gets the benefit.
Keep the rules straight:
- The student generally covers their own tax payable first.
- Only the remaining amount can be transferred.
- The supporting person claims the transferred amount on their own return.
Check the current transfer limit each year before deciding.
Fixing Missing Slips and Claiming Prior-Year Tuition
If you never claimed your tuition in an earlier year, you may still be able to. You can file a corrected or prior-year return to claim eligible fees. Missing slips can be requested from your school, and an official transcript can help prove what you paid.
Watch out: filing late can bring interest or penalties if you owe tax. Start by contacting your school for a replacement certificate, then file the missed years as soon as you can. Lira Tax & Accounting can help you with unfiled returns, including prior years. Our guide to filing back taxes and avoiding CRA penalties walks through the process step by step.
Filing Your Return With Lira Tax & Accounting
Claiming the tuition credit is simple once you know the steps, but it becomes harder with multiple slips, carried-forward amounts, or a transfer to a parent. Lira Tax & Accounting prepares personal returns for individuals across Canada. Get in touch to book a consultation and make sure your tuition credit works as hard for you as it should.
Add liratax.ca as a preferred source on Google →
Frequently Asked Questions
How do I claim the tuition tax credit on my tax return?
Enter the tuition amount from your T2202 slip on Schedule 11 of your federal return, then carry the result to the appropriate line on your return. Most tax software asks for the T2202 figures directly and fills in the schedule for you. Keep the slip with your records, because the Canada Revenue Agency can ask for it later even if you do not submit it with your return.
Which tuition fees are eligible for the tuition tax credit?
Eligible tuition fees are amounts paid to a qualifying educational institution in Canada for courses at the post-secondary level, and some courses that improve skills for an occupation. Check the official eligible tuition fees guidance for the details, and use the amount shown on your school's T2202 slip.
Can I claim tuition fees if I did not earn income?
Yes, but the credit is non-refundable, so it can only reduce tax you owe. If you had little or no taxable income, the credit may give you nothing this year. In that case, you can carry the unused amount forward to a later year or transfer part of the federal amount to an eligible family member, subject to the current limit. You still need to file a return to record the amount.
Can unused tuition tax credits be carried forward?
Yes. Any federal tuition amount you cannot use this year can be carried forward. Use it in a later year when you owe tax. Before you carry the amount forward, check whether transferring part of it to a supporting family member would reduce the household's total tax more. Schedule 11 shows your current-year amount, the amount you carry forward, and any amount transferred.