Last Updated: November 15, 2026
Quick Summary
Tax deductions vs tax credits both lower what you owe the CRA, but at different points. A deduction reduces taxable income before the rate applies, so its value depends on your marginal rate. A credit reduces the tax itself, so it is usually worth its full face amount, provided you have enough tax payable to use it.
- A deduction reduces the income that tax is calculated on, before the rate is applied.
- A non-refundable credit reduces tax payable dollar for dollar, but cannot push the bill below zero.
- At a 40% marginal rate, a $1,000 deduction saves about $400, versus $1,000 for a credit.
- Refundable credits can pay out even when you owe no tax, unlike non-refundable credits.
- Keep receipts with date, amount, vendor and business purpose, and split mixed personal and business costs.
Table of Contents
- Tax Deductions vs Tax Credits: How Each One Reduces Your Tax
- How a Tax Deduction Reduces Taxable Income
- How a Tax Credit Reduces Tax Payable
- Tax Deduction vs Tax Credit Examples
- Small Business Tax Deductions in Canada and the Business Expenses You Can Claim
- How to Organize Receipts for Business Expenses
- Book a Consultation to Review Your Deductions and Credits
- Frequently Asked Questions
Tax deductions vs tax credits both lower what you owe the Canada Revenue Agency, but they do it at different points in the calculation, and that difference changes how much each one saves. Owners often know they can claim expenses, but are not sure which claims shrink income and which shrink the final tax bill. The CRA's official guide groups deductions, credits and expenses as separate claim categories, and that split is the starting point for this article.
A deduction is an amount subtracted from income before tax is calculated (All deductions, credits and expenses - Personal income tax). A tax credit is an amount subtracted from the tax itself after it has been calculated. Both reduce tax, but a credit reduces the bill dollar for dollar, while a deduction reduces only the income on which tax is charged.
Tax Deductions vs Tax Credits: How Each One Reduces Your Tax
The short answer is that deductions reduce taxable income, and credits reduce tax payable. Because of that order, a deduction's value depends on your marginal tax rate, while a credit's value is generally fixed. Non-refundable credits can bring tax payable down to zero but will not produce a cheque beyond that.
Here is why it matters for a business owner. A deduction is worth more to someone in a higher bracket, because each dollar removed from income avoids tax at the top rate. A credit is worth the same to everyone who can use it. Knowing which type a given expense falls under helps you plan the year, not just the filing.
How a Tax Deduction Reduces Taxable Income
A deduction works before the tax rate is applied. If a business has $200,000 of taxable income and claims $10,000 of eligible expenses, it is taxed on $190,000 instead. The tax saved is that $10,000 multiplied by the rate that applies to the last dollars earned.
This is why deductions are often most valuable when income is high. Confirm which expenses qualify and keep records that support them.
How a Tax Credit Reduces Tax Payable
A credit is applied after tax is calculated, which is why its value does not depend on your bracket the way a deduction's does. If tax payable is $30,000 and a $3,000 credit applies, the bill falls to $27,000. The credit amount is the tax saved, regardless of the rate you are in, subject to the rules for that specific credit.
The part most explainers skip is that credits are not all the same. They fall into two broad groups, and the group determines whether a credit can produce money back.
Non-refundable credits can only reduce tax payable to zero. They cannot create a refund on their own. Most personal credits, the basic personal amount, the spousal or common-law partner amount, the Canada caregiver credit, the disability tax credit, tuition amounts, and medical expenses, are non-refundable (All deductions, credits and expenses - Personal income tax). When the eligible amount exceeds what you can use, the treatment of the excess depends on the credit: some amounts can be carried forward (tuition), some can be transferred to a spouse or common-law partner or a supporting person (disability, tuition, medical), and some are simply lost for the year. Check the specific credit before assuming the unused portion carries forward.
Refundable credits are paid even when tax payable is zero. They are not limited by the tax you owe, so they can generate a payment. Benefits delivered through the tax system, such as the Canada workers benefit and the GST/HST credit, are examples of refundable amounts. This is the key distinction many taxpayers miss: a refundable credit is not the same thing as a tax refund. A refund is the return of tax you overpaid through withholding or installments; a refundable credit is a benefit paid to you because you qualify, independent of how much tax you paid.
Credit ordering and limits matter too. Credits are applied against tax payable in a set order, and annual limits cap how much of a given credit can be claimed in a year, medical expenses, charitable donations, and tuition each have their own rules.
Watch out: claiming a non-refundable credit you cannot use does not create a refund, and carrying an amount forward when the credit does not permit it can trigger a reassessment. Confirm the carryforward and transfer rules for each credit before relying on them.
A practical way to think about it: a deduction changes the income the rates apply to, a non-refundable credit changes the tax after the rates apply, and a refundable credit can pay out even when there is no tax to reduce. Knowing which group a claim belongs to tells you whether it can lower your bill, be carried forward, be transferred, or produce a payment.
Tax Deduction vs Tax Credit Examples
A single dollar figure can produce very different savings depending on whether it is treated as a deduction or a credit, and the difference comes down to marginal tax rates. The clearest way to see it is to run the same amount through both treatments using federal rates and a provincial rate, then compare the result.
Take a taxpayer with $100,000 of taxable income in a province where the combined marginal rate on the next dollar is roughly 40% (federal plus provincial). Now compare a $1,000 deduction against a $1,000 non-refundable credit.
- $1,000 deduction: taxable income falls from $100,000 to $99,000. Tax saved is $1,000 × 40% = about $400. The value of the deduction is tied to the bracket the last dollar would have been taxed in.
- $1,000 non-refundable credit: tax payable falls by the credit amount, so the saving is the full $1,000, provided there is at least $1,000 of tax payable to offset. If tax payable were only $600, the credit would reduce the bill to zero and the remaining $400 would generally not be paid out; whether it can be carried forward depends on the specific credit.
That is why a credit often looks stronger on paper: at a 40% marginal rate, a $1,000 deduction saves about $400, while a $1,000 credit saves $1,000. But the comparison flips when the amounts differ. A $3,000 deduction at 40% saves about $1,200, more than a $1,000 credit. The lesson is to compare the actual dollar value of each claim at your marginal rate, not the headline amount.
Marginal rate matters most for deductions. A taxpayer in a lower bracket gets less from the same deduction: at a combined marginal rate of roughly 25%, a $1,000 deduction saves about $250, while at 40% it saves about $400. A non-refundable credit, by contrast, is generally worth the same dollar amount to anyone who has enough tax payable to use it.
Provincial credit rates vary, which is why the same credit can be worth different amounts depending on where you live.
A common pattern is to treat every claim as if it were worth its face value. In practice, a deduction is worth your marginal rate times the amount, and a non-refundable credit is worth the credit rate times the eligible amount, capped by the tax you actually owe. Running both numbers before year-end is what turns a list of claims into a plan.
The same dollar amount can save very different amounts depending on whether it is treated as a deduction or a credit.
| Treatment | How it reduces tax | Example value (per the article) |
|---|---|---|
| Deduction | Lowers taxable income before the rate applies | $1,000 at about 40% saves about $400 |
| Non-refundable credit | Lowers tax payable after the rate applies | $1,000 credit saves $1,000 if enough tax is owed |
| Non-refundable credit (limited tax) | Reduces tax only to zero, no payout | $600 tax owed with $1,000 credit leaves $400 unused |
| Deduction at lower rate | Value depends on marginal rate | $1,000 at about 25% saves about $250 |
Small Business Tax Deductions in Canada and the Business Expenses You Can Claim
Most business expenses that are incurred to earn income are deductible against that income. Common examples include office rent, supplies, advertising, professional fees, business insurance, vehicle costs (for the business-use portion), and salaries paid to employees. The rules for each category are set out in the CRA's guidance on business income and expenses, and the deductibility of any item depends on whether it was incurred to earn income and is reasonable in amount.
Personal expenses are not deductible, and a mixed-use expense must be split. Keep a clear record of the business portion, since that split is what the CRA will ask to see.
Business Expenses You Can Claim
Expenses that commonly qualify include:
- Rent for business premises
- Advertising and marketing costs
- Supplies consumed in the business
- Professional and accounting fees
- Business insurance premiums
- Business-use share of vehicle and travel costs
- Salaries and wages paid to employees
Each category has its own conditions, so confirm treatment before claiming.
How to Organize Receipts for Business Expenses
A deduction is only as good as the record behind it. Store each receipt with the date, amount, vendor, business purpose and any tax paid, and keep the originals or digital copies for the period the CRA requires. Sorting receipts monthly, rather than at tax time, catches missing items while they are still recoverable.
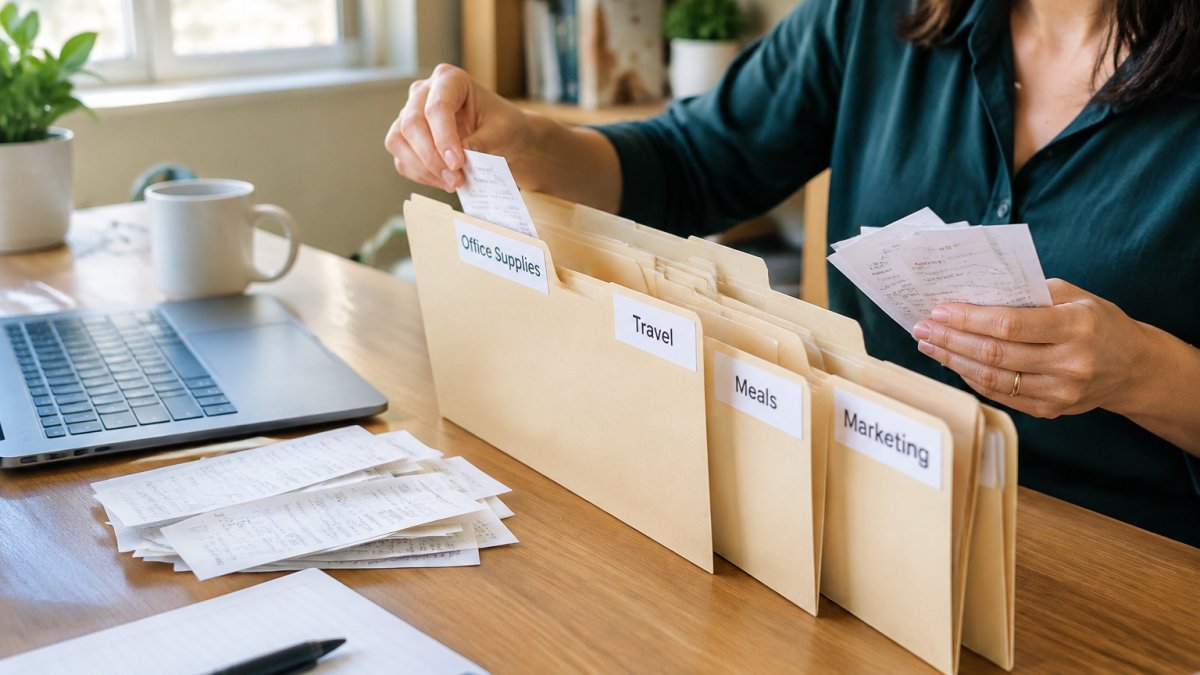
A simple system works well: one folder per expense category, a running spreadsheet, and a note on the back of any receipt with a mixed personal and business use.
Book a Consultation to Review Your Deductions and Credits
If you are unsure whether an expense is a deduction, a credit, or not claimable at all, the answer depends on your numbers and your structure. Lira Tax & Accounting can review your deductions and credits against your actual income and tax position. Book a consultation to walk through your situation.
Add liratax.ca as a preferred source on Google →Frequently Asked Questions
What is the difference between a tax deduction and a tax credit?
A tax deduction reduces your taxable income, so its value depends on your marginal tax rate. A tax credit reduces the tax you owe directly, dollar for dollar. Most credits in Canada are non-refundable, which means they can reduce your tax payable to zero but will not produce a refund beyond that. Deductions are claimed before tax is calculated, while credits are applied after. Knowing which category an expense falls into helps you estimate how much it actually saves you on your Canadian return.
Do tax credits reduce your taxable income or your tax bill?
Tax credits reduce your tax bill, not your taxable income. Taxable income is calculated after deductions are subtracted, and then tax is calculated on that amount. Credits are subtracted from the tax calculated, so a credit of CAD 500 lowers the tax you owe by CAD 500. Because most Canadian credits are non-refundable, they can bring your tax payable down to zero but not below it. Refundable credits are the exception and can produce a payment to you.
Which business expenses can be deducted from taxable income?
Business expenses that are reasonable and incurred to earn business income are generally deductible. Common examples include advertising, office supplies, rent, business insurance, software subscriptions and professional fees such as accounting. Some expenses, like meals and entertainment, are only partly deductible. Personal expenses cannot be claimed. Keeping supporting documents for each expense makes it easier to defend the claim if the Canada Revenue Agency asks for proof.
Can a small business claim both tax deductions and tax credits?
Yes. A small incorporated business can use deductions to reduce its net income and may also claim credits, such as certain investment tax credits for qualifying research and development work. The Small Business Deduction is a reduced corporate tax rate on active business income up to the applicable limit, and eligibility depends on the corporation's circumstances. Reviewing both categories together usually gives a more accurate picture of total tax savings.